
 Healthcare Software Development Services
 Healthcare App Development Services
 Real Estate Web Development Services
 Real Estate App Development Company
 E-Commerce App Development Services
 E-Commerce Web Development Services
 Blockchain E-commerce Development Company
 Fintech Software Development
 Fintech App Development Services
 E-Learning App Development Services
 Restaurant App Development Company
 Mobile Game Development Company
 Travel App Development Company
 Automotive Web Design
 AI Traffic Management System
 AI Inventory Management Software
 Logistics App Development Services
 Machine Learning Development
 ChatGPT integration services
 AI Development Company
 AI Integration Services
 Natural Language Processing Company
 Mobile App Development
 IOS App Development
 Android App Development
 Cross-Platform App Development
 Augmented Reality (AR) App Development
 Virtual Reality (VR) App Development
 Web App Development
 SaaS App Development
 Custom Software Development Services
 Flutter
 React Native
 Swift (IOS)
 Kotlin (Android)
 Mean Stack Development
 AngularJS Development
 MongoDB Development
 Nodejs Development
 Database Development
 Ruby on Rails Development
 Expressjs Development
 Full Stack Development
 Web Development Services
 Laravel Development
 LAMP Development
 Custom PHP Development
 .Net Development
 User Experience Design Services
 User Interface Design Services
 Automated Testing
 Manual Testing
 Digital Marketing Services
 Ride-Sharing And Taxi Services
 Food Delivery Services
 Grocery Delivery Services
 Transportation And Logistics
 Car Wash App
 Home Services App
 ERP Development Services
 CMS Development Services
 LMS Development
 CRM Development
 DevOps Development Services
 AI Business Solutions
 AI Cloud Solutions
 AI Chatbot Development
 API Development
 Blockchain Product Development
 Cryptocurrency Wallet Development
 About Talentelgia
 Our Team
 Our Culture
 Healthcare App Development Services
 Real Estate Web Development Services
 E-Commerce App Development Services
 E-Commerce Web Development Services
 Blockchain E-commerce
Development Company
 Fintech App Development Services
 Blockchain Fintech
Development Company
 E-Learning App Development Services
 Restaurant App Development Company
 Mobile Game Development Company
 Travel App Development Company
 AI Traffic Management System
 AI Inventory Management Software
 AI Development Company
 ChatGPT integration services
 AI Integration Services
 Machine Learning Development
 Machine learning consulting services
 Blockchain Development
 Blockchain Software Development
 Smart contract development company
 NFT marketplace development services
 Asset tokenization companies
 DeFi Wallet Development Company
 IOS App Development
 Android App Development
 Cross-Platform App Development
 Augmented Reality (AR) App
Development
 Virtual Reality (VR) App Development
 Web App Development
 Flutter
 React
Native
 Swift
(IOS)
 Kotlin (Android)
 MEAN Stack Development
 AngularJS Development
 MongoDB Development
 Nodejs Development
 Database development services
 Expressjs Development
 Full Stack Development
 Web Development Services
 Laravel Development
 LAMP
Development
 Custom PHP Development
 User Experience Design Services
 User Interface Design Services
 Automated Testing
 Manual
Testing
 About Talentelgia
 Our Team
 Our Culture

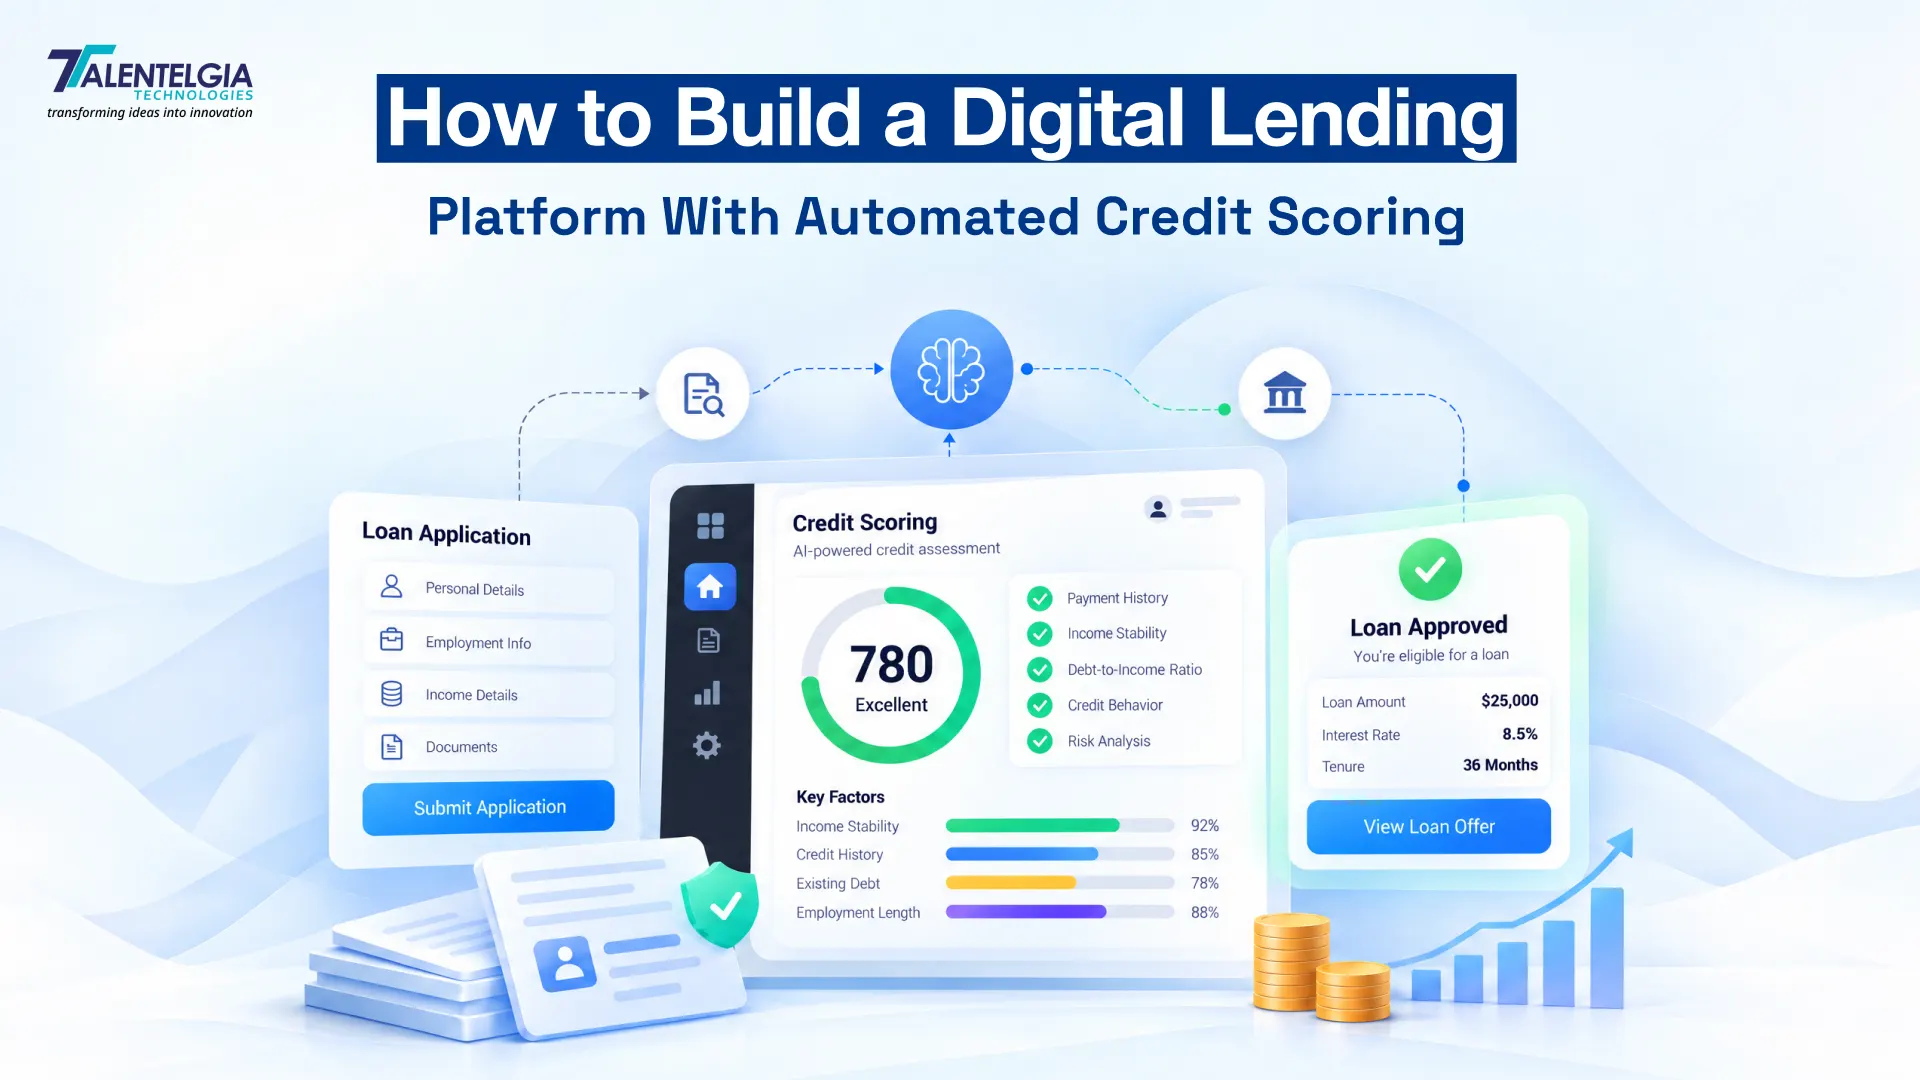
To build a digital lending platform with automated credit scoring, you need more than a loan application and a credit-score API. The platform must connect borrower onboarding, identity verification, financial data, credit rules, risk models, underwriting, approval, disbursement, and loan servicing into a single workflow.
The credit scoring layer evaluates an applicant’s risk, but it should not operate in isolation. A complete digital lending software platform needs to determine which data to use, validate that data, apply the lender’s credit policy, decide whether an application should be approved or reviewed, and record why that decision was made. Once the loan is disbursed, the platform also needs to manage repayments and capture performance data that can improve future risk decisions.
That makes lending platform development an architectural challenge as much as a product-development exercise. This guide explains the core components, automated credit scoring workflow, technical architecture, integrations, compliance considerations, development process, build-versus-buy options, and costs involved in building a production-ready digital lending platform.
What Is Digital Lending Software?
Digital lending software is technology that manages the lending lifecycle through digital workflows, from application and credit assessment through approval, disbursement, servicing, and collections. A complete platform may combine a loan origination system (LOS), credit decision engine, data integrations, loan management system (LMS), borrower portal, payment infrastructure, and risk monitoring.
That distinction matters because a borrower-facing application is only the visible part of a lending operation. The platform behind it has to coordinate information from multiple systems and turn that information into controlled lending decisions.
| A typical lifecycle looks like this:Application → Verification → Credit Assessment → Underwriting → Decision → Offer → Disbursement → Servicing → Repayment → Collections |
The exact architecture depends on the lender, product, jurisdiction, and operating model. A consumer lender may need instant decisioning and high-volume bureau integrations, while an SME lender may require higher income, cash-flow, business, and manual-underwriting workflows.
Digital Lending Platform vs. Loan Application
| Loan application | Digital lending platform |
| Captures borrower information | Manages the broader lending lifecycle |
| Provides a borrower interface | Connects borrower, lender, risk, and operational workflows |
| May submit information for manual review | Can automate eligibility and underwriting |
| Usually focused on origination | Covers origination and may extend through servicing and collections |
| Limited business logic | Contains configurable policies, rules, workflows, and decisioning |
| May use external APIs | Orchestrates multiple financial and operational integrations |
This is why digital lending software should be designed as financial infrastructure rather than treated as a mobile or web application alone. The user interface is important, but the system’s reliability ultimately depends on what happens behind the application form.
How Automated Credit Scoring Works Inside a Lending Platform
Automated credit scoring converts borrower and financial information into a structured assessment of credit risk. In a production platform, however, the score should not independently determine whether someone receives a loan. The decision engine combines the score with eligibility rules, lender policy, fraud signals, affordability checks, loan-product constraints, and sometimes human review.
| The basic flow is:Borrower Data → Validation → Financial Data → Features → Rules → Credit Model → Risk Score → Decision → Explanation → Monitoring |
This separation between the model and the decision policy is important. A model can estimate risk, while a rules engine determines whether that risk fits the lender’s current policy.
What Data Does the Credit Scoring System Use?
The data required depends on the product and market. A lender may combine application information with credit-bureau records, income, employment, existing obligations, repayment history, bank or transaction data, and other permitted financial information.
Alternative data can also be considered where it is legally permissible, relevant to the lending decision, obtained with appropriate consent, and demonstrably useful. It should not be added simply because more data is available.
The platform therefore needs a controlled data layer that records:
- Where each data point came from
- When it was obtained
- Whether the applicant consented to its use
- How the value was validated
- Which decisioning components used it
- Which model or policy version consumed it
This becomes particularly important when a lender needs to investigate a decision later.
Rules-Based Scoring vs. Machine Learning
Not every lending product needs machine learning. A rules-based system can handle deterministic requirements such as minimum age, geography, product eligibility, maximum loan amount, or existing exposure limits. Traditional scorecards can then combine variables into a statistical risk assessment.
Machine-learning models can be useful when a lender has sufficient historical outcome data and a legitimate use case for identifying more complex relationships. The model might estimate default probability, detect unusual application patterns, or support risk segmentation.
A practical architecture often combines the approaches:
| Decision layer | Example role |
|---|---|
| Eligibility rules | Reject applications that fail basic requirements |
| Policy rules | Apply lender-specific risk and exposure limits |
| Scorecard/model | Estimate credit risk |
| Fraud engine | Identify suspicious or inconsistent applications |
| Decision engine | Combine signals and determine the workflow |
| Human review | Handle exceptions and borderline cases |
The important engineering principle is to keep these layers configurable. If every policy change requires developers to modify application code, the lending platform becomes difficult to maintain as products and risk policies evolve.
What Happens After the Credit Score?
A credit score is an input to a decision, not necessarily the decision itself.
A typical workflow might look like:
Risk Score → Policy Threshold → Approve / Refer / Decline
An approved application may then move into pricing, credit-limit calculation, offer generation, e-signature, and disbursement. A borderline application can be routed to an underwriter with the relevant information already assembled.
A declined application may also require a documented reason. In the United States, Regulation B requires specific reasons for adverse action, and the CFPB has explicitly stated that using a complex or “black-box” algorithm does not remove that obligation.
That means the decisioning architecture should be designed to preserve the relationship between the data considered, model or rules used, decision produced, and reason communicated.
Core Components of a Digital Lending Platform
A production platform should be organized around the lending lifecycle rather than a collection of disconnected features.
Digital Borrower Onboarding
The onboarding layer captures the application and establishes the borrower’s identity and consent. Depending on the product, this can include registration, identity verification, document collection, income information, bank-data consent, loan-purpose information, and electronic signatures.
The goal is not simply to collect as much information as possible. The workflow should request the information necessary for the product and pass validated data into downstream systems without repeatedly asking the borrower for the same information.
Loan Origination System (LOS)
The LOS manages the journey from application through underwriting and funding. It coordinates application status, verification, document requirements, credit checks, offers, approvals, and handoffs to disbursement or servicing.
A configurable LOS is particularly valuable when the lender supports multiple products. Different products can use different eligibility rules, documentation requirements, approval thresholds, and workflows without creating entirely separate applications.
Credit Scoring and Decision Engine
The decision engine is where credit policy becomes executable software. It can retrieve external data, run eligibility rules, call scoring models, evaluate fraud signals, calculate affordability measures, and route the application based on the resulting conditions.
Good credit scoring software should therefore do more than return a numerical score. It should preserve the inputs, calculations, policy version, model version, and resulting decision so that the lender can reconstruct how an application was handled.
Fraud and Identity Verification
Credit risk and fraud risk are related but different problems. A borrower may have an acceptable credit profile while an application contains suspicious identity, device, document, or behavioral signals.
Fraud controls can therefore operate before or alongside credit decisioning. Depending on the product, the platform may integrate identity verification, document verification, device intelligence, transaction analysis, sanctions screening, or other risk services.
Loan Management System
The LMS takes over once the loan is funded. It maintains balances, repayment schedules, interest and fee calculations, payment allocation, statements, delinquency status, and collections workflows.
This post-origination layer should not be treated as an afterthought. The performance of funded loans generates the outcome data needed to understand whether the original credit decisions were effective.
Borrower and Operations Portals
A complete platform usually needs more than one user experience.
The borrower may need to:
- Track an application
- Review an offer
- Sign documents
- View balances
- Make payments
- Download statements
- Raise service requests
Operations and risk teams may need:
- Application queues
- Underwriting workbenches
- Decision explanations
- Exception handling
- Portfolio dashboards
- Audit records
- Policy controls
Separating these experiences allows the platform to give each user the information and controls appropriate to their role.
Technical Architecture for Automated Credit Decisioning
The architecture should keep customer interaction, financial workflows, decisioning, integrations, and data management logically separated while allowing them to communicate through well-defined APIs and events.
A conceptual architecture looks like this:
Borrower
│
Web / Mobile Application
│
API Gateway
│
Loan Origination System
│
┌──────────────┴──────────────┐
│ │
Data & Verification Fraud Checks
│ │
└──────────────┬──────────────┘
│
Decision Engine
│
┌──────────┴──────────┐
│ │
Policy Rules Credit Model
│ │
└──────────┬──────────┘
│
Approve / Review / Decline
│
Loan Management System
│
Payments / Collections
│
Analytics & Monitoring
The exact technology stack can vary. A typical implementation might use a web or mobile frontend, an API layer, a transactional relational database, a dedicated decisioning service, a separate model-serving environment, event-driven integrations, and centralized observability.
The important architectural decision is not whether one framework is better than another. It is whether the components provide transaction integrity, security, traceability, scalability, and controlled change.
Financial calculations also deserve special treatment. Loan balances, interest, repayments, fees, and allocations should use appropriate monetary representations and deterministic calculation rules. A scoring model can tolerate statistical variation; a loan ledger cannot.
The model-serving layer should also be separated from the core loan ledger. If a model is updated, the change should not alter historical financial records or make past decisions impossible to reconstruct.
Integrations Required for a Digital Lending Platform
Integrations are often where lending projects become more complicated than expected. The platform may need to exchange data with several external systems before a single application reaches a final decision.
Common integrations include:
- Credit bureaus
- KYC and identity providers
- Bank-data or open-banking services
- Income-verification providers
- Fraud and risk services
- Payment gateways
- Banking or core-lending systems
- E-signature providers
- Notification platforms
- CRM systems
- Accounting and ERP systems
- Analytics platforms
External providers can time out, return incomplete data, change schemas, reject requests, or become temporarily unavailable.
A resilient lending platform development approach therefore includes authentication, validation, retries, idempotency, timeout handling, fallback states, webhook processing, and audit logging.
Planning a connected lending architecture? Talk to our fintech software development company about designing the integrations around your lending workflow.
How to Build a Digital Lending Platform Step by Step
1. Define the Lending Product
Start with the product rather than the interface. Determine whether the platform will support consumer loans, SME lending, personal loans, BNPL, secured lending, or another product.
The product determines the data required, risk model, repayment structure, compliance requirements, and operational workflow.
2. Define the Credit Policy
Before developing a model, establish the lender’s actual risk policy.
Define eligibility criteria, minimum requirements, exposure limits, acceptable risk bands, pricing rules, referral conditions, and manual-review requirements.
This policy becomes the foundation for the decision engine.
3. Map Regulatory Requirements
Regulation should influence architecture from the beginning rather than being added before launch.
The requirements can affect consent, data storage, disclosures, decision explanations, audit trails, borrower communications, lending-service-provider relationships, and record retention.
For example, India’s 2025 Digital Lending Directions established requirements around digital lending activities conducted by regulated entities, including arrangements with lending service providers, borrower data, disclosures, grievance handling, and other controls.
Because regulatory requirements change and differ by jurisdiction, the platform should be designed around the specific lender, product, and market rather than copying another country’s workflow.
4. Design the Lending Workflow
| Map every state an application can enter:Started → Submitted → Verification → Scoring → Review → Approved/Declined → Offered → Signed → Disbursed → Servicing |
Also define what happens when something goes wrong. Missing information, failed verification, unavailable bureau data, suspected fraud, or a borderline score should each have an explicit workflow.
5. Select the Data Sources
Identify which data is genuinely required for the credit policy. Then evaluate providers for coverage, accuracy, latency, API reliability, consent requirements, cost, and regulatory compatibility.
Starting with providers before defining the decision policy can lead to unnecessary integrations and data collection.
6. Design the Decision Engine
Separate the decision engine from the user interface.
Rules, scorecards, models, thresholds, manual-review conditions, and decision outputs should be represented as configurable components where practical.
This allows the risk team to change a lending policy without rebuilding the borrower application.
7. Develop the LOS and LMS
Build origination and servicing around the defined lifecycle.
The LOS handles the pre-funding process; the LMS manages the loan after funding. Their handoff should be explicit and reliable, especially around disbursement, repayment schedules, and ledger state.
8. Build or Integrate the Scoring System
If the lender has an established model, integrate it through a controlled scoring service. If a proprietary model needs to be developed, establish the data pipeline, feature definitions, training process, validation approach, model registry, deployment process, and monitoring before production use.
9. Integrate External Services
Connect bureaus, KYC, banking data, payments, fraud services, e-signature, notifications, and other systems required by the workflow.
Test failure conditions as seriously as successful responses.
10. Test Credit Models and Business Rules
Functional testing alone is insufficient. Test whether rules produce the intended decisions, whether model inputs are correct, whether edge cases are routed appropriately, and whether decision outputs remain consistent after software changes.
11. Complete Security and Compliance Testing
Test authentication, authorization, encryption, APIs, data handling, audit logs, infrastructure, third-party integrations, and failure scenarios.
Financial applications should also undergo appropriate security and compliance review for their target market.
12. Pilot and Monitor
Do not treat launch as the end of the project. Monitor approval rates, manual-review rates, repayment behavior, fraud signals, model performance, system failures, and decision distributions.
The first production loans provide outcome data that can help validate whether the platform behaves as intended.
Also Read: How to Create a Fintech App?
How to Make Automated Credit Scoring Explainable and Auditable
Explainability needs to be designed into the decision pipeline rather than added after the model has been deployed.
For each decision, the platform should be able to identify:
- Which data was used
- Which rules were applied
- Which model version was used
- What score or risk estimate was produced
- Which threshold or policy determined the outcome
- Whether a human changed the automated result
- What reason codes were generated
- When the decision occurred
This creates a decision record that can be investigated later.
For US lending, the CFPB’s Regulation B interpretation says that adverse-action reasons must relate to factors actually considered or scored, including when a credit scoring system is used. The CFPB has also stated that complex algorithms do not eliminate the requirement to provide specific reasons.
Model governance is broader than explainability. The revised 2026 interagency US model-risk guidance emphasizes model development and use, testing, validation and monitoring, and governance and controls, while taking a risk-based approach that varies with the organization’s model risk profile and complexity.
That makes model versioning, validation records, performance monitoring, and controlled deployment important parts of the engineering architecture.
Need an auditable scoring workflow? Talentelgia can help connect decisioning, APIs, application logic, and monitoring into one platform.
Build vs. Buy: Which Approach Is Right for Digital Lending Software?
There is no universal answer. The right approach depends on whether the lending technology itself is a competitive advantage.
| Approach | Best suited for | Main trade-off |
|---|---|---|
| Buy | Standard lending workflows and faster deployment | Less control over proprietary workflows |
| Build | Differentiated credit policy, products, or integrations | Higher engineering and maintenance requirements |
| Hybrid | Custom decisioning with established external services | Requires careful integration architecture |
Buying can make sense when the lending process closely resembles established industry workflows and speed matters more than deep customization.
Building becomes more attractive when proprietary underwriting logic, unusual lending products, complex integrations, or a differentiated borrower experience are central to the business.
A hybrid approach is often practical. A lender might build its own LOS and decision engine while using external providers for KYC, credit data, payments, identity verification, and e-signatures.
The decision should therefore be based on the parts of the lending stack the business needs to control. Rebuilding commodity infrastructure rarely creates an advantage, while outsourcing the core decisioning logic may limit differentiation.
How Much Does It Cost to Build Digital Lending Software?
There is no reliable universal price for a digital lending platform because scope varies substantially between an MVP, a single-product lender, and a multi-market lending operation.
Current published development estimates illustrate the range. YuSMP’s 2026 lending-software guide estimates $70,000–$110,000 for an MVP with core decisioning and $120,000–$210,000 for a production LOS, while its broader loan-origination guide puts a focused custom LOS at $200,000–$450,000 and a broader platform at 450,000–900,000+. These are vendor estimates rather than universal market benchmarks.
Talentelgia’s published general custom-software ranges are lower for simpler scopes: $5,000–$40,000 for a focused MVP, $40,000–$100,000 for a mid-complexity business application, and $100,000–$500,000+ for complex enterprise software. Those figures apply to custom fintech software development generally, not specifically to regulated lending platforms.
For lending, the major cost drivers are usually:
- Number and complexity of loan products
- LOS and LMS scope
- Credit scoring requirements
- Number of external integrations
- KYC and fraud infrastructure
- Payment and banking integrations
- Regulatory and security requirements
- Mobile and web applications
- Data engineering
- Model development and validation
- Monitoring and ongoing maintenance
The most useful way to estimate a project is therefore to define the lending workflow and integration scope first, then price the engineering required for each component.
How Talentelgia Can Help Build Digital Lending Software
Building a lending platform requires more than frontend and backend development. The product has to connect financial workflows, APIs, data, decisioning, security, mobile experiences, and operational systems without losing control over how decisions are made.
Talentelgia’s current fintech software development services cover financial applications across lending and other financial workflows, with API-driven architecture, financial integrations, automated workflows, AI/ML capabilities, role-based access, cloud infrastructure, and security-focused engineering.
Its custom software practice also covers API integration, event-driven architecture, workflow automation, machine learning, analytics, modernization, and connected business systems. Talentelgia specifically lists lending and investment platforms among the financial systems it develops.
For organizations considering fintech development services, that can mean building the borrower experience alongside the backend systems that support onboarding, decisioning, payments, and servicing. For more complex products, custom fintech development can also provide greater control over proprietary workflows and integrations.
Ready to build custom lending software? Talk to Talentelgia about your digital lending platform.
Frequently Asked Questions
Digital lending software manages the lending lifecycle through digital workflows, including borrower onboarding, identity verification, credit assessment, underwriting, approval, disbursement, servicing, repayment, and collections. A complete platform typically combines loan origination, decisioning, financial integrations, operational tools, and post-disbursement management rather than functioning as a borrower-facing application alone.
Automated credit scoring evaluates borrower information against defined risk factors, rules, scorecards, or machine-learning models to estimate credit risk. The resulting score is then combined with eligibility criteria, lender policies, fraud signals, and other decisioning conditions to approve, decline, or route an application for additional review.
The required data depends on the loan product, jurisdiction, and credit policy. Common inputs include application details, credit-bureau information, income, existing obligations, repayment history, and permitted financial or transaction data. Alternative data may also be used when it is relevant, lawful, consented to, and properly governed.
Custom digital lending software can range from tens of thousands to several hundred thousand dollars, depending on scope. Current published 2026 vendor estimates range from roughly $70,000 for a focused MVP to $900,000 or more for broader platforms. Integrations, compliance, scoring, security, servicing, and multiple products can significantly increase costs.
Development time depends on the number of loan products, integrations, scoring requirements, regulatory scope, and platform complexity. A focused MVP may take several months, while a production platform with custom decisioning, servicing, integrations, security controls, and multiple workflows can require substantially longer development and testing.
Common integrations include credit bureaus, identity and KYC providers, bank-data services, fraud tools, payment gateways, e-signature providers, banking systems, notification services, CRM platforms, and analytics tools. The exact combination depends on the lending product, market, operating model, borrower data requirements, and regulatory responsibilities of the lender.
Neither approach is universally required. Rules are useful for deterministic eligibility and policy requirements, while statistical or machine-learning models can estimate more complex credit risk when sufficient quality data exists. Many platforms combine both, using rules as policy guardrails and models as one component of broader automated decisioning.
Yes. A properly designed platform can support multiple products by separating shared services from configurable product rules and workflows. Each product can define its own eligibility criteria, scoring approach, limits, pricing, documentation, approval routing, and repayment structure while continuing to use common identity, integration, servicing, and reporting infrastructure.
Hiring fintech app developers makes more sense when the business needs proprietary lending workflows, specialized credit decisioning, unusual integrations, differentiated borrower experiences, or control over its technology architecture. Buying can be more practical when requirements closely match an established platform and faster deployment matters more than deep customization.
Yes. Talentelgia’s current FinTech services cover lending applications alongside financial integrations, AI/ML, APIs, mobile and web development, cloud infrastructure, security, and custom software engineering. Its published capabilities support custom financial workflows rather than limiting development to a standard borrower application or single technology layer.





 Sales Enquiries:
 Business queries:
 HR:


